Stocks enter Friday facing competing forces. Investors are attempting to stabilize markets after a volatile week, but persistent inflation, rising borrowing costs and uncertainty surrounding Nvidia have weakened confidence in a sustained year-end rally. The 10-year Treasury yield remained near 5.13%. That combination leaves equities vulnerable if earnings expectations fail to keep pace with financing costs.
The inflation backdrop remains difficult. U.S. consumer prices increased 0.4% in October, while core prices rose 0.3%. Shelter, food and energy all contributed to the monthly increase. Today’s producer-price report showed a 0.3% monthly advance, below the 0.4% forecast, but annual wholesale inflation accelerated to 6.5%. The smaller monthly increase offers some relief, although the broader price trend continues to complicate the Federal Reserve’s decisions.
For stocks, renewed monetary tightening creates pressure through several channels. Higher bond yields reduce the present value of future earnings, raise refinancing costs and give investors a more competitive alternative to equities. Companies dependent on borrowing to fund expansion face a particularly demanding environment. Even businesses with strong revenue growth can experience falling share prices when investors assign a lower valuation to those revenues.
Nvidia has added a separate source of instability. Jensen Huang’s departure and Colette Kress’s appointment as interim CEO have raised questions about leadership continuity at the company central to the AI investment cycle. Nvidia recovered part of Thursday’s initial decline, but its weakness still contributed to a lower U.S. market close.
The danger for the broader sector extends beyond Nvidia’s daily share-price movements. AI investment connects chipmakers, memory suppliers, networking companies, cloud operators, lenders and major technology customers. A sustained loss of confidence could make financing more expensive, delay infrastructure projects and force investors to reassess expected returns across that network.
This creates a plausible path from a company-specific crisis to a wider sector correction. If cloud operators struggle to finance expansion, orders for chips, servers and networking equipment could slow. Suppliers might then face weaker growth just as their customers incur rising depreciation, power and interest expenses. Falling earnings estimates combined with lower valuation multiples would intensify the pressure.
There is also a risk that investors have extrapolated AI spending growth too far into the future. Substantial demand can coexist with excessive valuations and poor investment returns. The critical question is whether spending produces enough incremental revenue and cash flow to justify the capital committed. Nvidia’s leadership transition could accelerate that reassessment, particularly among companies whose valuations depend on uninterrupted expansion.
Canada faces overlapping pressures. The TSX fell 0.75% on Thursday morning to 36,137.19, with materials losing 3.2% and financials declining 0.5%. Energy gained as crude advanced, while Canadian technology also finished higher. That divergence shows how commodity exposure and individual business relationships can produce different outcomes within the same market.
Through year-end, Canadian banks, property companies and consumer businesses remain sensitive to debt servicing, mortgage renewals and household spending. Energy producers could benefit from stronger crude, but an extended oil rally would increase inflation pressure elsewhere. Gold miners remain exposed to metal prices, operating costs and currency movements. Canadian AI suppliers could attract business from competing platforms, although a broader reduction in infrastructure spending would challenge the entire supply chain.
Trade restrictions, tariffs and tighter semiconductor export controls add further uncertainty. Middle East tensions could disrupt energy supplies or shipping, while a stronger U.S. dollar can pressure commodities and overseas earnings. Heavy government borrowing and fiscal uncertainty could also keep longer-term yields elevated, even if economic growth slows.
The current year-end base case outlook is continued volatility with selective opportunities, with limited confidence in a broad, uninterrupted rally. A more bullish outcome would require cooling inflation, stabilizing yields, credible AI earnings guidance and improving participation beyond a small group of large companies.
The downside scenario becomes more serious if inflation remains persistent while growth weakens. Further tightening, reduced AI spending and falling earnings estimates could turn sector weakness into a broader correction. This would represent a stagflation risk, particularly for highly indebted and expensive growth companies.
A year-end recovery remains possible, but seasonal optimism alone offers little protection against deteriorating fundamentals. Through December, the strongest evidence for a durable advance would be improving cash generation, stable customer orders and broader market participation. Until those conditions become clearer, analysts and investors are holding a cautious assessment of valuations, financing needs and the durability of earnings.
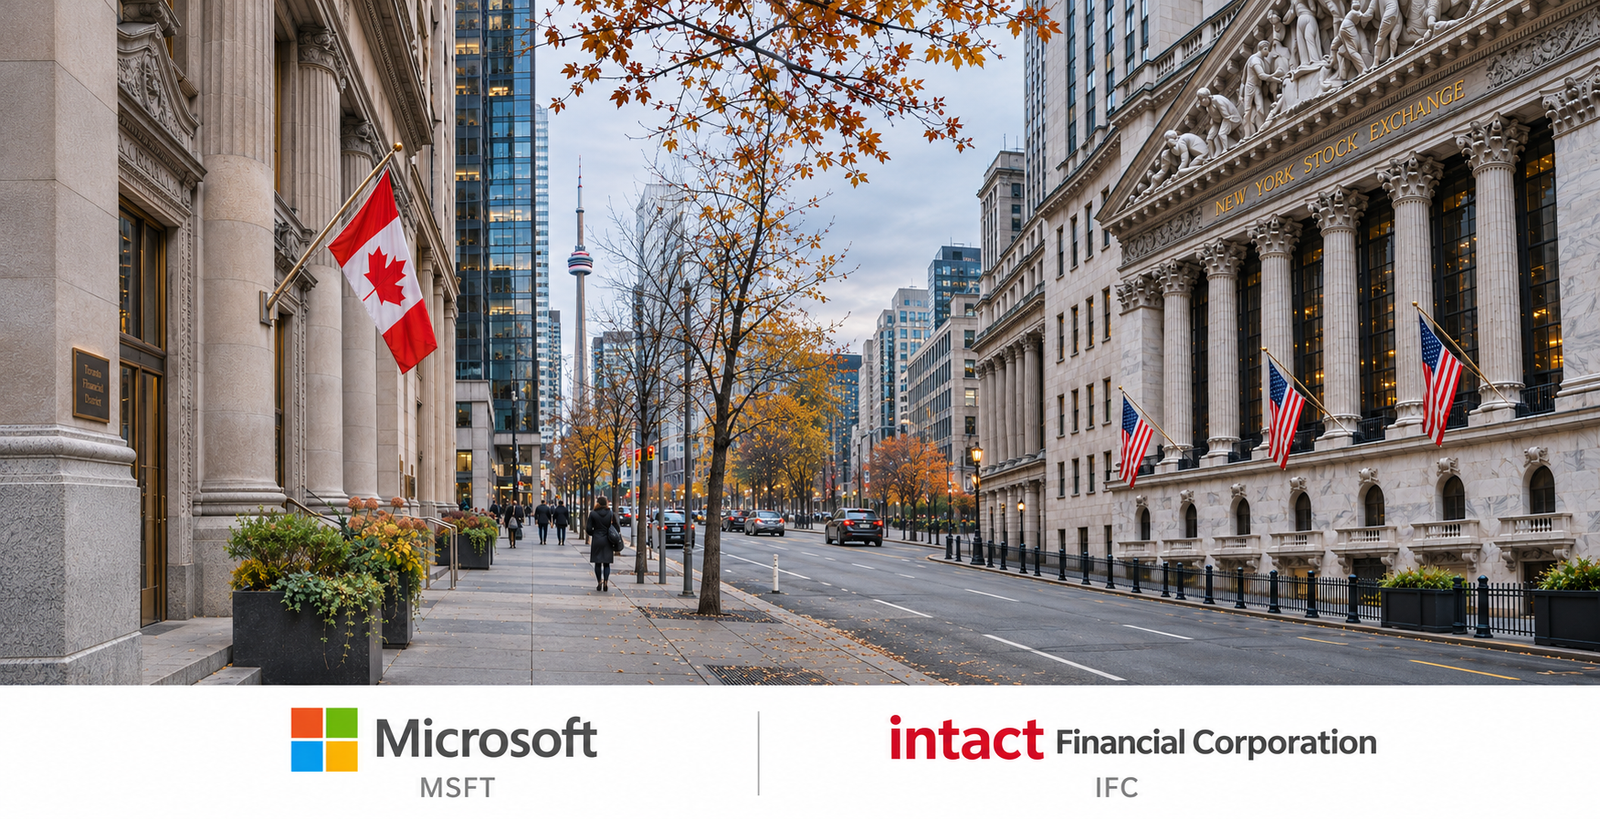
Two Stocks to Consider in this Market: Microsoft (MSFT) is a top U.S. growth stock to consider over the next 12–24 months, supported by its cloud business, recurring software revenue and AI opportunities. Analyst consensus is a “Buy” , with an average 12-month target of US$627 per share, showing the potential for significant upside. However, heavy AI spending and higher interest rates remain risks.
Intact Financial (IFC:CA ) is a top Canadian defensive stock, supported by resilient insurance demand, profitable underwriting and a strong capital position. The analyst consensus is “Buy” , with an average 12-month target of C$306.50 per share, however severe weather and rising claims costs remain the main risks.