Celestica, Air Canada and Barrick Mining
November 9, 2026
Canadian stock markets are advancing sharply to begin the trading week, supported by renewed interest in technology companies, strengthening precious metals prices and improving investor sentiment as crude oil prices retreat. The S&P/TSX Composite Index climbed approximately 1.3% during morning trading, reflecting broad-based buying across several sectors.
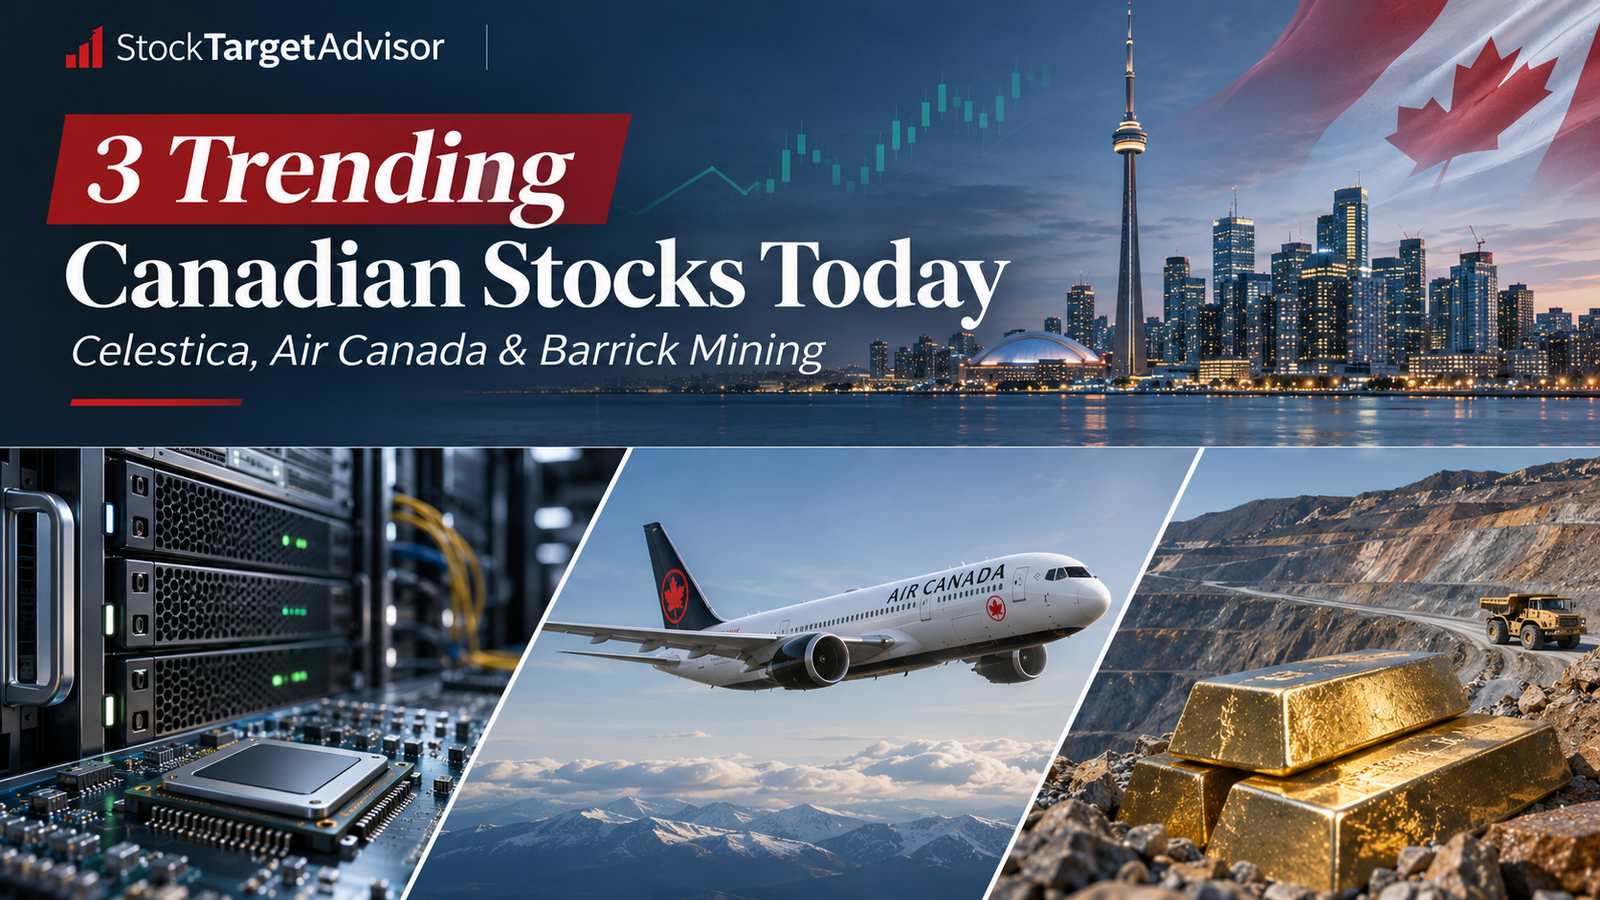
Among today’s most notable Canadian stocks are Celestica (CLS:CA), Air Canada (AC:CA) and Barrick Mining (ABX:CA). Each company represents a different investment opportunity, with investors focusing on artificial intelligence infrastructure, improving airline economics and stronger profitability in the precious metals sector. Recent analyst ratings and price-target revisions provide additional insight into institutional expectations and potential valuation risks.
Celestica (CLS:CA): AI Infrastructure Growth Drives Investor Interest
Celestica Inc. is attracting renewed investor attention as demand for artificial intelligence infrastructure continues supporting significant revenue and earnings growth. Shares advanced approximately 7.8% to C$315.00 during morning trading, making the company one of the strongest performers among major Canadian stocks.
Celestica recently reported exceptional third-quarter financial results, generating US$5.83 billion in revenue, representing an 83% increase from the previous year. Adjusted earnings per share reached US$3.30, compared with US$1.58 a year earlier, reflecting the company’s growing exposure to high-performance computing and data-centre infrastructure.
Management also increased its 2026 financial outlook, projecting approximately US$21 billion in annual revenue and adjusted earnings of US$11.55 per share. Demand for networking equipment, advanced computing systems and hyperscale data-centre infrastructure remains an important growth driver.
Recent Analyst Ratings: Bank of America maintained its Buy recommendation on November 4 but reduced its 12-month price target to US$450 from US$500. CIBC also maintained a Buy recommendation with a US$500 target on October 29. The recommendations reflect continued confidence in Celestica’s earnings growth and AI infrastructure exposure, although Bank of America’s target reduction suggests greater caution concerning valuation following the company’s strong share-price performance.
From an investment perspective, Celestica offers substantial exposure to the expanding AI infrastructure market, but its strong share-price performance introduces valuation risk. Investors should assess whether future earnings growth can justify elevated expectations, particularly if technology spending slows.
Outlook: Bullish long-term fundamentals, supported by positive analyst recommendations and accelerating earnings growth, with a cautious near-term assessment given valuation sensitivity and the possibility of profit-taking following strong gains.
Air Canada (AC:CA): Falling Oil Prices Support a Potential Recovery
Air Canada is experiencing renewed buying interest as declining oil prices improve expectations for airline operating costs. Shares gained approximately 5.5% to C$23.11 during morning trading, reflecting increasing investor confidence in the potential for improved profitability.
The airline recently reported record third-quarter operating revenue of approximately C$6.98 billion, supported by a 14% increase in total unit revenue. Adjusted EBITDA reached C$936 million, while management continued strengthening the company’s balance sheet through debt repayments and share repurchases.
However, Air Canada also reduced its full-year adjusted EBITDA forecast to C$2.4 billion–C$2.7 billion from its previous C$2.9 billion–C$3.2 billion outlook, primarily because of higher fuel-cost expectations. This highlights the company’s sensitivity to energy prices and operating expenses.
Recent Analyst Ratings: RBC Capital Markets maintained its Outperform recommendation on November 2 while reducing its 12-month price target to C$28 from C$37. CIBC also maintained its positive Buy recommendation but lowered its price target to C$31 from C$40. These revisions indicate that analysts continue to recognize recovery potential while adopting more conservative earnings and profitability assumptions. RBC’s target represents approximately 21% potential upside, while CIBC’s target suggests approximately 34% upside over the next 12 months.
Today’s retreat in crude oil prices is particularly relevant because lower fuel costs could improve airline margins if the decline is sustained. Air Canada also has an authorized share repurchase program beginning November 9th, providing another potential source of shareholder value over time.
Outlook: Cautiously bullish recovery potential, supported by improving fuel-cost expectations, record revenues and analyst price targets above the current share price. Nevertheless, weaker consumer spending, labour expenses and volatile jet fuel prices remain important risks.
Barrick Mining (ABX:CA): Strong Earnings and Gold Prices Support Shares
Barrick Mining Corporation is another Canadian stock attracting investor attention following the release of its third-quarter financial results. Shares advanced approximately 3.5% to C$59.23 during morning trading, supported by stronger precious metals sentiment and encouraging financial performance.
Barrick reported quarterly revenue of US$5.07 billion, an increase of 22% year over year. Adjusted earnings reached US$0.82 per share, representing a 41% increase from the corresponding period last year, while quarterly gold production totaled approximately 816,000 ounces.
The company also generated US$2.49 billion in operating cash flow and maintained full-year gold production guidance of 2.90 million to 3.25 million ounces. Management returned approximately US$1.04 billion to shareholders through dividends and share repurchases, demonstrating a commitment to capital discipline.
Recent Analyst Ratings: RBC Capital Markets maintained its Outperform recommendation in late October, with a reported U.S. price target of US$53. National Bank maintained its Buy recommendation on October 20th while reducing its Canadian-dollar price target to C$72.50 from C$75. Stifel Nicolaus also maintained its Buy rating but lowered its target to C$84 from C$90 on October 19th. Relative to Barrick’s November 9th’s morning share price of C$59.23, National Bank’s target implies approximately 22% potential upside, while Stifel’s target suggests approximately 42%. These earlier analyst revisions indicate a generally positive outlook for the company’s earnings and cash-flow prospects, although target reductions highlight some caution concerning operating costs and valuation.
Despite improving profitability, rising production costs remain an important concern. Barrick’s all-in sustaining costs increased to US$1,911 per ounce, reflecting higher operating expenses and capital requirements. Consequently, future profitability will remain sensitive to gold prices, production efficiency and operational performance.
Outlook: Constructive, supported by stronger earnings, significant operating cash flow, positive analyst ratings and shareholder returns.
STA Research (StockTargetAdvisor.com) is a independent Investment Research company that specializes in stock forecasting and analysis with integrated AI, based on our platform stocktargetadvisor.com, EST 2007.
Related research
How Trump’s Tariffs Could Shake Up Magna International’s Auto Parts Business
STA Research (Rank#25) Maintained “Hold” Rating on Starbucks, $110 target (SBUX:NSD)
Bank of Canada Looks to Pause rates as Recession Looms
Paradigm Capital Upgrades Cameco to Buy and Lowers Target to C$130
Weekly Stock Market Outlook: Nvidia, AI Stocks and Inflation Data in Focus as Wall Street Looks for a Recovery
TD Securities Cuts Trisura Group to a Hold and Lowers Target to C$45
A monthly perspective in your inbox.
Five research sections in the STA Research Professional Newsletter.