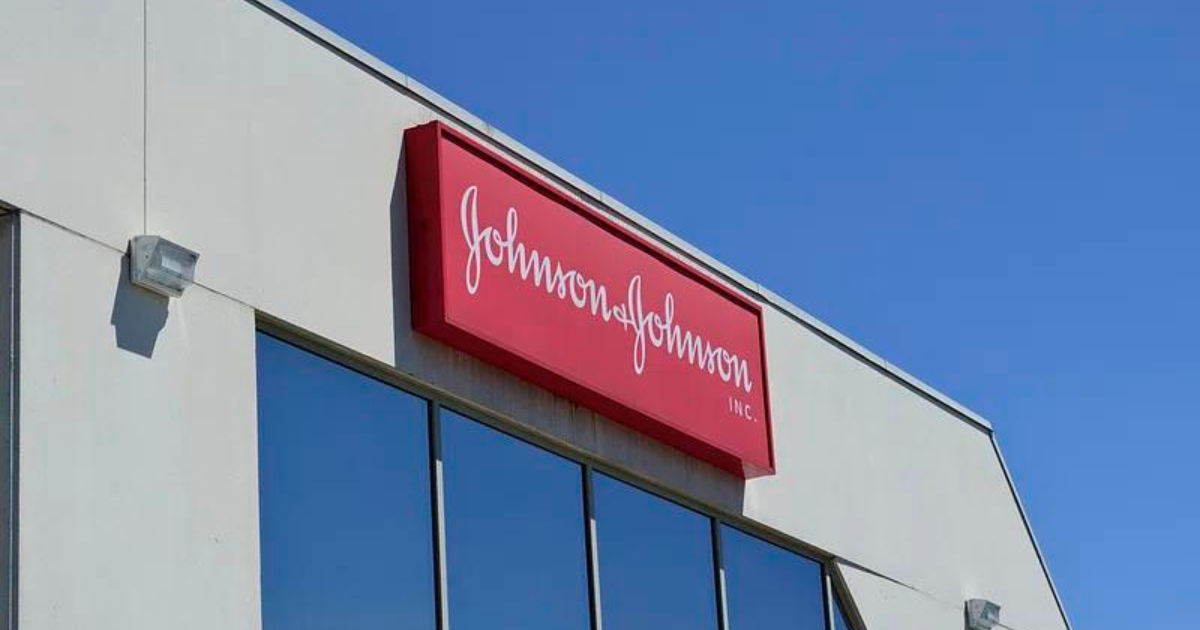
Johnson & Johnson (JNJ)
RBC Capital Markets recently updated their coverage on JNJ’s stock, and maintained their “Outperform” rating and raised its 12 month price target to US$290 per share.
Operating Performance and Earnings Outlook
Johnson & Johnson’s second-quarter 2026 results reported sales of US$25.3 billion, up 6.6%, diluted EPS of US$2.27 and adjusted EPS of US$2.90. The company raised its full-year outlook to a reported-sales midpoint of US$101.1 billion and an adjusted-EPS midpoint of US$11.68. Adjusted EPS is a non-GAAP measure, and guidance is management’s forecast.
The investment case depends on durable growth across innovative medicines and medical technology. New products must contribute enough earnings to offset competitive pressure on established treatments. For shareholders, sales growth is most valuable when it supports sustainable profit and cash generation.
Valuation and Key Risks
The constructive scenario assumes successful commercialization and steady MedTech demand. A cautious scenario includes slower adoption, pricing pressure, patent-related competition or adverse legal outcomes. A premium valuation requires confidence that earnings can remain resilient beyond one forecast year.
Stock Analysis Outlook
Johnson & Johnson’s stock forecast is cautiously positive, with a “Buy” analyst consensus rating and a US$280 12 month price target, implying 10% upside. However, the “Strong Sell” technical signal suggests near-term weakness, creating a divide between analysts’ positive outlook and current price momentum.
More StockTargetAdvisor analyst updates.
STA Research (StockTargetAdvisor.com) is a independent Investment Research company that specializes in stock forecasting and analysis with integrated AI, based on our platform stocktargetadvisor.com, EST 2007.