Canadian Tire (CTC.A:CA)
(About StockTargetAdvisor.com (STA Research) is a Canadian investment research company specializing in advanced stock research and analysis).
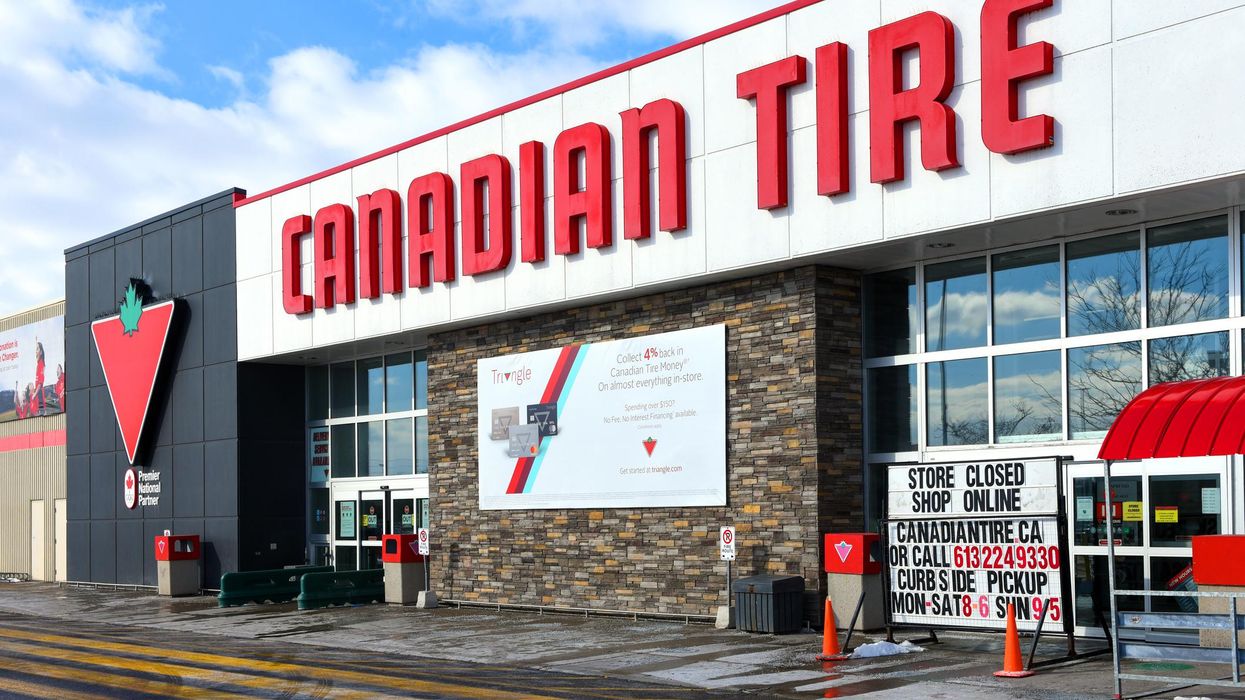
The Canadian Tire Corp. recently reported a strong third-quarter financial result, with improving profitability and renewed investor confidence in its operating outlook. Shares advanced 7.22% on November 12th to close at C$219.77, approaching their reported 52-week high of C$222.71. Despite Canada’s weakening employment environment, persistent cost-of-living pressures and cautious consumer spending, Canadian Tire’s diversified retail operations, established brand portfolio and expanding loyalty ecosystem continue to support its competitive position. The recent share-price rally reflects improving investor confidence, although the stock is now trading above its supplied 12-month analyst consensus target.
Canadian Tire currently has an analyst consensus rating of “Buy”, with an average 12-month price target of C$214.50 per share. Based on the November 12th closing price of C$219.77, this forecast represents approximately 2.5% potential downside over the next 12 months, excluding dividends. Recent brokerage recommendations demonstrate a mixed but generally constructive outlook. RBC Capital Markets maintained its Outperform rating with a C$230 price target, while Stifel maintained its Buy recommendation with a C$220 target. National Bank maintained its Sector Perform rating and raised its price target to C$214 from C$209. BMO maintained its Hold recommendation with a C$204 target, while TD Securities maintained its Hold rating with a C$210 target. These differences suggest that analysts remain confident in Canadian Tire’s underlying business performance but have varying expectations for future valuation and earnings growth following the recent share-price appreciation.
Canadian Tire’s third-quarter 2026 financial results demonstrated improving operating momentum, with consolidated revenue increasing to C$4.32 billion from C$4.11 billion in the prior-year period. Comparable retail sales increased 3.2%, while retail revenue advanced 5.0%, supported by stronger performance across the company’s principal operating banners. Canadian Tire Retail, SportChek and Mark’s each generated comparable sales growth exceeding 3%, while e-commerce revenue increased 15.3% and loyalty-related sales advanced 6.3%. Diluted earnings per share from continuing operations increased 36.4% to C$4.27, while normalized diluted earnings per share rose 13.0%. These results indicate that Canadian Tire continues to improve operating efficiency and profitability despite economic pressures affecting household purchasing power and discretionary consumer spending.
From a fundamental valuation perspective, Canadian Tire trades at approximately 15.9 times trailing earnings and 14.8 times forward earnings, based on the previously reported market data. These valuation multiples suggest a relatively measured earnings valuation compared with some higher-growth consumer companies, although they must be considered alongside the company’s cyclical operating exposure and modest near-term analyst return expectations. Canadian Tire also increased its annual dividend to C$7.30 per share, marking its seventeenth consecutive year of dividend growth. Based on the November 12 closing price of C$219.77, the annual dividend represents an indicative yield of approximately 3.3%. The combination of improving earnings, established retail operations and consistent shareholder distributions provides a favourable foundation for longer-term investment returns.
Technical analysis currently indicates a “Strong Buy” signal, reflecting positive share-price momentum and strengthening investor confidence. Canadian Tire’s 7.22% advance on November 12 and its proximity to the reported C$222.71 52-week high reinforce the bullish near-term technical outlook. Immediate resistance can be monitored around C$222 to C$223, with a sustained breakout above this region potentially supporting additional upward momentum. Initial technical support appears around C$210 to C$212, followed by a secondary support region near C$205. Although the Strong Buy signal suggests favourable momentum, the stock’s sharp recent appreciation also increases the possibility of short-term profit-taking or consolidation, particularly as its current price exceeds the consensus target.
Canadian Tire’s investment outlook remains sensitive to Canada’s slowing economic growth, weakening employment conditions, elevated household debt and persistent inflationary pressures. While the company’s automotive products, household essentials and value-oriented merchandise provide relatively recurring demand, discretionary categories such as sporting goods, home improvement and seasonal merchandise can experience greater volatility during periods of weaker consumer confidence. Canadian Tire’s Financial Services operations also introduce exposure to consumer credit conditions, making employment trends, household borrowing costs and repayment performance important considerations. Competitive pricing, promotional activity, inventory management and operating cost inflation could further influence future revenue growth and profitability.
The current outlook remains positive with the bullish technical outlook and a cautiously positive longer-term fundamental assessment for Canadian Tire.The analyst consensus Buy rating and Strong Buy technical signal are supported by improving earnings, positive comparable-store sales growth, expanding digital operations and consistent dividend increases. Canadian Tire remains a financially established Canadian retail business with favourable operating momentum, but sustained share-price appreciation will likely depend on additional earnings growth, resilient consumer demand and further upward revisions to analyst expectations.
STA Research (StockTargetAdvisor.com) is a independent Investment Research company that specializes in stock forecasting and analysis with integrated AI, based on our platform stocktargetadvisor.com, EST 2007.
Related research
How Trump’s Tariffs Could Shake Up Magna International’s Auto Parts Business
STA Research (Rank#25) Maintained “Hold” Rating on Starbucks, $110 target (SBUX:NSD)
Bank of Canada Looks to Pause rates as Recession Looms
Canadian Stock Market Outlook: Rising Job Losses, Inflation and Economic Pressures- 3 Stocks Positioned to Outperform
Shopify (SHOP:CA) Strong Fundamentals Support Bullish Outlook Despite Technical Weakness
Celestica Inc. (CLS:CA) Analysts Update Stock Forecasts
A monthly perspective in your inbox.
Five research sections in the STA Research Professional Newsletter.